


 Follow Us
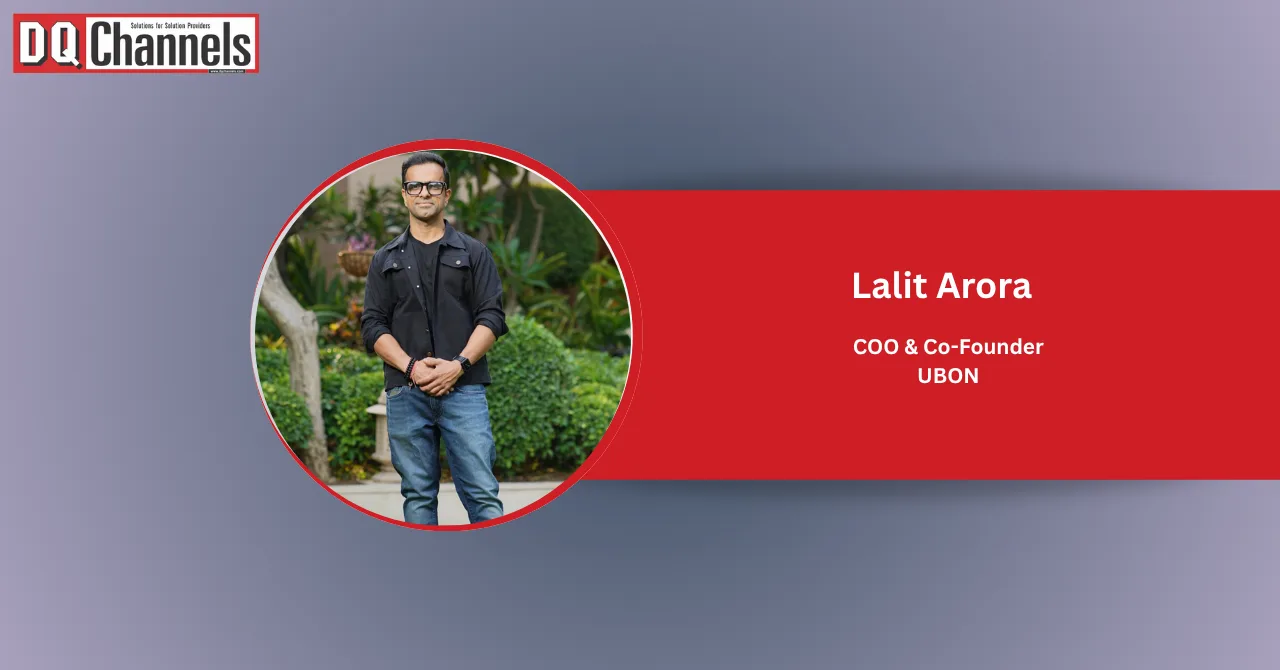
India’s next growth story is not limited to the biggest cities. For UBON, Tier-2 and Tier-3 markets are becoming a central part of the business, with demand shaped by younger consumers, wider connectivity, changing payment habits and stronger appetite for consumer electronics.
Lalit Arora, COO & Co-Founder, UBON, says the shift is already visible in the company’s category. He points to markets such as Indore, Coimbatore, Lucknow, Surat and Patna as some of the fastest-expanding locations for smartphone and audio accessory demand.
But reaching Bharat is not simply about adding more distributors. Arora argues that the bigger challenge is building a local ecosystem where retail, e-commerce, financing, inventory, service and partner profitability work together.
Tier-2 and Tier-3 markets are becoming a core growth engine
For UBON, smaller cities are no longer a secondary opportunity.
“They are no longer a secondary bet, they are where most of our incremental growth is actually coming from,” says Arora.
He points to industry data showing online shopping in Tier-2 cities growing between 25% and 30%, with these markets contributing more than half of incremental order volume nationally. Tier-3 cities, he adds, are growing from a smaller base but at a faster year-on-year rate.
Within UBON’s category, cities including Indore, Coimbatore, Lucknow, Surat and Patna are highlighted as important growth markets.
Several factors are pushing this demand forward. Falling device prices, wider 4G and 5G availability and a younger, more brand-aware customer base are changing how consumers in smaller cities approach smartphones and audio accessories.
That changes the channel equation too.
The opportunity is no longer simply about geographic expansion. It is about understanding how consumers in these markets discover products, make payments, evaluate brands and seek support after purchase.
The Bharat go-to-market model is becoming a hybrid one
Arora does not see regional distribution, local retail and e-commerce as competing choices.
Instead, he argues that brands need to combine them.
“The winning approach blends a strong regional distributor network for physical reach with e-commerce for visibility and price discovery.”
That distinction matters. E-commerce can help consumers discover products and compare prices, while local retail still plays an important role in building confidence.
Arora points to cash on delivery as one indication that online trust has not completely replaced offline credibility. He says recent D2C market analysis puts COD at roughly 55% to 65% of Tier-2 and Tier-3 online orders.
Quick commerce is also entering the equation. Arora says it has expanded into more than 80 Tier-2 and Tier-3 cities this year, creating another discovery route for categories such as accessories.
The result is a more complicated channel structure. A consumer may discover a product online, compare prices on an e-commerce platform, see it at a local retailer and then decide where to buy.
For brands, that means the channel strategy has to work across all those touchpoints.
Pricing, inventory and financing have to fit the local buyer
One of the more important points in Arora’s responses is that affordability does not simply mean offering the lowest price.
“Pricing in these markets isn't just about being cheaper, it's about being right for the wallet cycle of the buyer,” he says.
That has led UBON towards tiered product portfolios, with entry points below flagship pricing while retaining what Arora describes as the brand experience.
Inventory is another issue. Smaller cities can be less forgiving when products are unavailable because consumers may not have several alternative stores nearby.
Financing also has a role. Easier consumer credit and EMI options are being identified as drivers of durable-goods demand in smaller towns, according to the industry bodies Arora refers to.
For channel partners, this creates a balancing act. They need enough inventory to meet demand without tying up too much working capital.
Local retailers remain a trust layer
Technology may have changed how consumers discover products, but Arora says local retailers still have considerable influence.
“A local retailer's word still carries more weight than an online review in a lot of Tier-2 and Tier-3 towns,” he says, particularly for electronics where customers may want to see and hold a product before purchasing.
That makes partner enablement more than a sales exercise.
UBON has focused on training store staff so they can explain product features rather than competing only on price. Arora also highlights margin structures, faster replenishment and vernacular marketing support.
The language used to explain a product can matter as much as the product message itself.
“A partner who can explain a product in the local language and idiom converts far better than any national ad campaign we run,” Arora says.
For brands expanding deeper into Bharat, this puts the local partner closer to the customer experience.
After-sales service can decide whether growth lasts
Selling a product is only one part of the relationship.
Arora sees service and repairs as critical to sustaining consumer electronics demand in smaller cities. The reason is straightforward: when customers cannot get a product repaired locally, the problem can quickly become a problem for the brand.
“This is where a lot of brands quietly lose the trust they worked hard to build,” he says.
UBON has therefore focused on extending service reach beyond state capitals. For first-time electronics buyers in particular, the after-sales experience can become the real test of whether a brand deserves another purchase.
Arora says markets with stronger service infrastructure show better repeat-purchase behaviour than markets where the model is based largely on sale-and-forget distribution.
That also changes the role of the channel partner. A retailer that can provide credible local service becomes more than a sales point. It becomes part of the brand relationship.
Growth does not automatically mean healthy partner economics
There is another side to the Bharat opportunity.
Volume may be growing, but Arora describes partner profitability as “genuinely mixed”. Smaller partners can face working-capital pressure, particularly when commerce continues to rely heavily on cash on delivery.
A sale can therefore be profitable on paper while still creating a cash-flow problem.
Price sensitivity adds another pressure. Smaller-city consumers can be more price-conscious than metro buyers, which can compress partner margins.
Arora's answer is to focus on faster payment cycles and predictable restocking rather than pushing volume alone.
This is an important distinction. A larger distribution footprint does not necessarily mean a healthier channel.
“Reach without partner profitability just produces churn,” Arora says.
What does winning Bharat actually mean?
For UBON, the answer is broader than sales.
“Honestly, it has to be all four, or the win doesn't last,” says Arora, referring to wider reach, higher revenue, stronger partner profitability and a deeper local ecosystem.
That approach puts sustainability at the centre of the Bharat strategy.
A distribution network can create reach. E-commerce can create visibility. Competitive pricing can create initial demand. But without local service and healthy partner economics, those gains may be difficult to sustain.
Arora's larger point is that Bharat cannot be treated simply as an extension of the metro market.
It requires a different combination of pricing, product choices, channel management, financing, local-language engagement, inventory planning and service.
As he puts it, “Revenue without a real local ecosystem evaporates the moment a competitor undercuts you on price.”
For consumer electronics brands, that may be the more important lesson in the current Tier-2 and Tier-3 expansion story. The opportunity is not just to sell more products in smaller cities. It is to build the local relationships and infrastructure that can keep customers, retailers and distributors in the ecosystem.
Read More:
Enterprise AI partners: Why domain expertise and integration now matter
ADCTA and AU Small Finance Bank support taxpayer registration camps in Nehru Place
When green dashboards hide red flags: Building outcome-ready IT operations
AI-powered managed services: Where the next channel opportunity lies